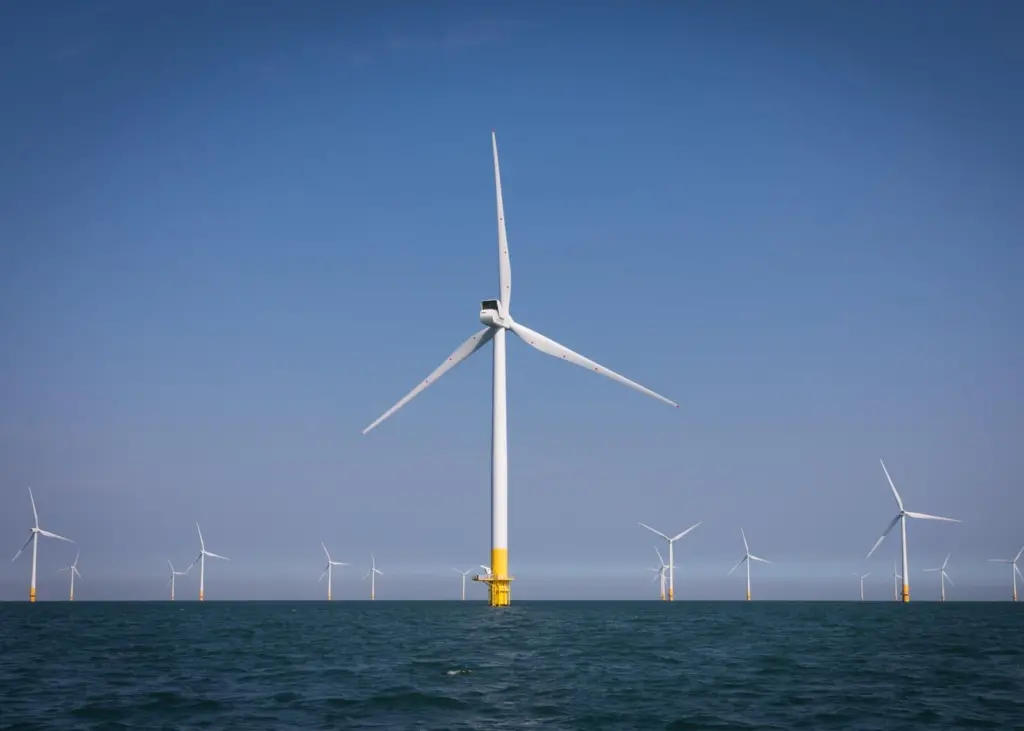
This is according to clean energy consultancy K2 Management, which has forecast an increase in both partnerships and OEM acquisitions as investors look to secure supply chain confidence.
Will Sheard, director of analysis and due diligence at K2 Management, said: To boost broader investor confidence in the sector, funding and consolidation will be critical.”
Sheard believes that in order to move beyond the R&D phase and into full-scale commercial deployment, floating wind technology, and with it the supply chain, must be consolidated as per conventional offshore foundations previously.
He explained in more detail: “The big OEMs are cautious about taking on R&D risk…but this attitude is forcing the risk and R&D pressure elsewhere – and now we have as many base concepts as we do base OEMs.
“Base OEMs are typically smaller businesses without the balance sheet to drive convergence of design and therefore commercial scalability. In order to achieve floating wind at the required scale, however, investors need confidence in the supply chain – and there are potential procurement risks in having such a disparity of options available from highly specialised firms.”
Sheard continued: “As such, there must be an increase in both OEM acquisitions and technology partnerships. To secure the future of floating wind in the next decade, we expect to see an increase in larger players – including many from the diversified O&G industry with experience working with floating substructures – acquiring smaller base manufacturers, therefore providing the balance sheet backing that will support the transition to commercial scale. This will make R&D conversations between turbine manufacturers and base manufacturers equitable, and accelerate development of complete, connected, commercially viable floating wind structures.”
By Rebecca Jeffrey