

New blow for Harland & Wolff as contract terminated
A contract initally won by Harland & Wolff to build four floating pontoons for the Falkland Islands has fallen apart.
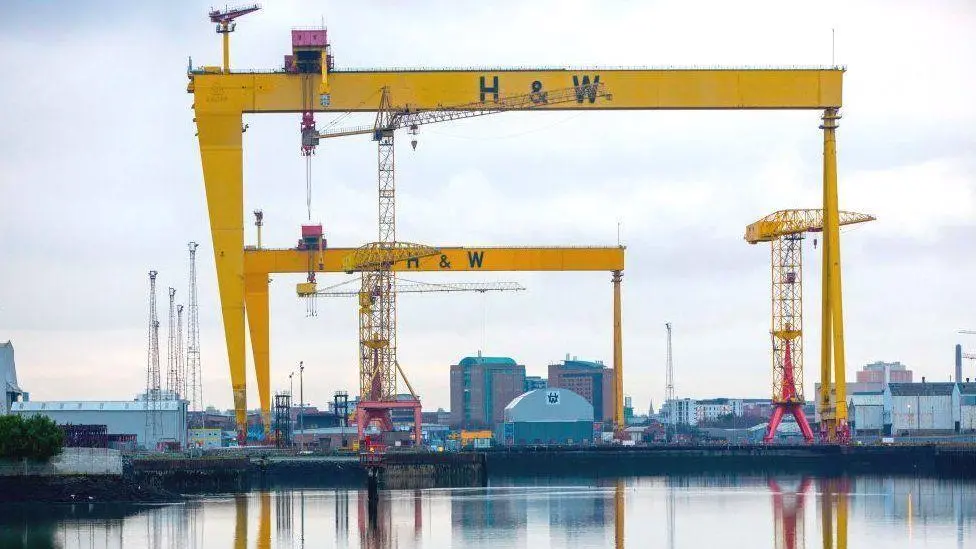
Iconic Belfast shipbuilder Harland & Wolff has so far refused to comment on the current changing of the guard and withdrawn financing plaguing the troubled firm, apart from standard ‘business as usual’ statements.
Now it has suffered another blow – the termination of a $120 million deal for a port replacement project on the Falkland Islands.
The project, known as FIPASS, would have involved the build, transport and installation of four 90m-long floating pontoons. When it was announced preferred bidder in March this year, Harland & Wolff said it built on an ‘already great legacy’ with the Falklands, where 40 years ago it built the six linked barges that make up the islands’ port facility.
“This project not only signifies a step forward for the Falkland Islands but also for Harland & Wolff as we continue to build on our legacy of excellence and innovation,” said John Wood, CEO at the time, now having made way for a new board and interim executive chair Russell Downs.
In yesterday’s statement, the Falkland Islands Government (FIG) said it had been unable to reach ‘a mutually acceptable commercial position’ with Harland & Wolff.
“After careful consideration, it has been determined that proceeding with an alternative partner will best ensure the project’s successful delivery within the required cost, schedule and risk parameters. During the pre-contract negotiations, no monies have been paid to Harland and Wolff,” it said.
Blow after blow
The blow comes after popular Harland & Wolff CEO John Wood left the firm when the UK government refused to stand by a £200 million loan guarantee that had been agreed under the previous government.
The following day, a lifeline loan totalling £19.5 million was secured from Riverstone Credit Opportunities Income (RCOI), part of Riverstone Investment Group, which brings the total loans from Riverstone to £140 million, according to RCOI’s statement.
The £19.5 million is ‘part of a larger effort to stabilise the liquidity of Harland & Wolff and help facilitate a long-term capital solution’, it says.
New interim chief Downs also announced on August 1 that it was pulling the plug on its planned Damen-built fast ferry operations on the British Isles of Scilly ‘to refocus on core business functions’.
“As the new board assesses all aspects of the group’s activity, the ferry operation was identified as being overly ambitious given the current circumstances,” said Downs. “Therefore, we have made the difficult decision to withdraw support for this operation, believing it to be in the best interest of the group.”
RCOI has refused to comment on queries raised by Maritime Journal as to the terms of the loans and management situation.
Related Articles
 OTHER NEWS
 OTHER NEWS
 SPONSOREDSTORY