Offshore wind – building an industry
A report prepared for RenewableUK and The Crown Estate by BVG Associates has set out the scale of opportunities for UK offshore wind at what is a critical time in the industry’s development.
The report is entitled Building an Industry and Maf Smith, deputy chief executive at RenewableUK, sets the scene in the report’s foreword: “2013 therefore marks a fork in the road. We can look back and see the achievements in what is a world leading sector. And we can look forwards and work out how we best build on this. This means the UK avoiding the road less travelled. The UK needs to step confidently onto the busier, faster road. Down this route lays hustle and bustle, risks and rewards. Also down this road lays continued UK market leadership, cost reduction and clear UK economic benefit.”
Mr Smith describes 2013 as a year of consequences for the offshore wind sector, a year of delivery, with Greater Gabbard and London Array alone connecting over 1.1GW of energy to the grid, over 3GW now in operation overall and still only half way through the year which also sees publication of the government’s Industrial Strategy for Offshore Wind along with continuing progress with Electricity Market Reform, events that will define what happens in the next phase of UK offshore wind.
The report is aimed at government and industry and provides evidence on the potential scale of activity that will be generated by offshore wind projects both in the UK and the rest of Europe.
TWO SCENARIOS
Building an Industry is an update of a similar analysis published in 2010 and two scenarios are considered. Scenario 1 sees significant growth beginning in 2018 with 13GW installed by 2020 and 33GW by 2030. Scenario 2 is more ambitious and assumes a cost-effective industry with sustained investment in new capacity and decreasing energy cost, driven by confidence in a long term future with rapid growth in installation leading to 18GW by 2020 contributing to a European total of 36GW. Throughout the report it is stressed the lower scenario runs a greater risk of not stimulating inward investment in the UK.
Charts indicate a rapidly developing supply chain, many companies already with advanced investment plans. Indeed 40% of facilities required for Scenario 1 are already operational, a third also operational for Scenario 2. Less than a quarter of these are, however, located or planned to be located in the UK, market uncertainty inhibiting future infrastructure investment.
Despite strong progress, the industry faces a significant short term challenge with a forecast dip in activity this year and next, largely due to lack of project consents granted between 2009 and 2012. The Rounds 1 and 2 extensions initiative aimed at bridging the gap has not progressed as quickly as predicted due to consenting requirements and industry priorities, the added capacity expected after 2015 rather than during the anticipated slow-down. This short term dip in UK demand is expected to be balanced by a forecast increase in activity across the rest of Europe during 2013 and 2014. Herein lays the conundrum for development of the UK supply chain at this critical time. For companies to meet demands from the rapidly growing European market in the second half of the decade major investment decisions need to be made in the next two to three years and once that commitment is made, future investment is likely to take place at that location. Despite the sustained level of UK activity and investment, the report states much larger opportunities remain as the vast majority of components and services are still being supplied from the continent, adding that the expected confidence following ambitious market plans has been shaken by the lack of clarity about future government plans due to the EMR initiative, the market lull in 2013 and 2014 doing little to encourage supply chain development.
Industry feedback suggests that measures in the Energy Bill will likely provide greater confidence about medium term market stability but legislative progress must be maintained to provide confidence beyond 2014 and avoid suppliers delaying investment in existing locations elsewhere on the continent.
BIGGER SCALE
Looking to the future, a key factor is that as the size of turbines and foundations increases, progressing from marinised onshore to dedicated offshore models, most companies will not have capacity to produce next generation designs in existing facilities, coastal locations being an attractive option. Preparing for the future takes time, the report finding that for production capacity to be ready for the 2017 forecast jump in UK demand with Scenario 2, significant product development, including prototype and demonstration operations, will need to be underway by 2014. The significant point here is that commitment to major infrastructure investment will be needed in or before 2014.
Assuming an annual production rate of 100 units per year for Scenario 1, there is a market need for three to four average sized facilities each for nacelles, blades and towers (or a combination of fewer, larger facilities). Industry feedback is that up to half this capacity could be provided by a single UK based player. Two or three additional UK players would be needed with Scenario 2.
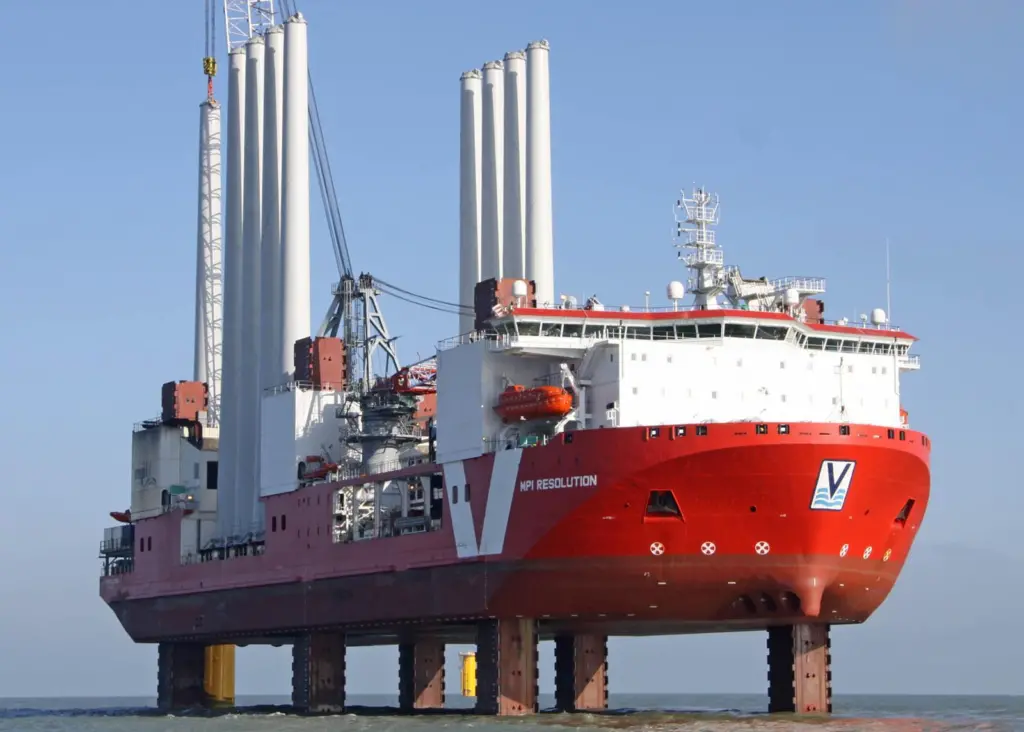
Uncertainty exists about what will be the dominant long term foundation design. As monopiles reach their limits of suitability, various alternative fixed and floating, steel or concrete designs are now appearing, there seeming to be no shortage of choices in this department. An interesting point made in the report is that concrete gravity based units with the turbine installed onshore could all but eliminate the need for an installation vessel. In reality of course different conditions mean large windfarms will likely require a combination of designs, both for practicality and economic reasons. It is important also to remember that as rated turbine capacity increases, the number of foundations required per gigawatt is reduced with obvious costs benefits, including cost per foundation not rising proportionally. Foundation manufacturing facilities are fairly well catered for given the backdrop of the oil and gas industry, but it is noted that the resurgence in North Sea oil and gas activity means the case for significant investment in wind only facilities may become more challenging with uncertain offshore wind market conditions.
The report also considers in detail areas surrounding sub-stations and convertor stations (AC versus DC), cable market conditions, installation and O&M vessels, and the all important influence of the wider European market.
In conclusion, it is clear that significant increases in installation activities will take place from 2017, whatever the scenario. Project developers will need to commit to suppliers in 2014 and 2015, these suppliers in turn needing to decide the location of new facilities and port infrastructure in the next two to three years. These decisions will determine the long term shape of the supply chain for the next 20 years.
The report describes competition between the UK and the rest of Europe to secure jobs as “fierce”, each country having particular advantages. The UK has a world leading track record in offshore wind delivery with a significant pipeline of future projects. Germany and Denmark already have existing supply chains, but often not in the right locations. France meanwhile, is designing its licencing process around promotion of indigenous supply chain growth.
The report states the competitive advantage of the UK as the dominant market should not be underestimated, but the domestic market has lost momentum. Clearly any market uncertainty and reduced ambition risks the situation that the UK is just one market among many. In this case, the argument for investing in the UK is less compelling. Perhaps the most important statement is: “if the UK is to succeed in building a dynamic domestic supply chain, two things must happen. First, Government must demonstrate that it will support sufficiently strong market demand to ensure that the UK market remains ahead of other markets. It also needs to consider the market beyond 2020, as the relatively low margins available in the offshore wind sector generally require major investment decisions to be taken with a business plan of 10 years or more. Second, project developers need to underline the importance of UK content, such that the supply chain sees the business advantages in being UK based”.
By Peter Barker
Related Articles
 MARINE RENEWABLES
 OFFSHORE RENEWABLES
 OTHER NEWS