Reducing Germany’s offshore wind costs
Reducing the cost of offshore wind is vital for development of the industry and a report for Germany’s offshore wind industry has produced findings mirroring the challenges facing other countries including the UK.
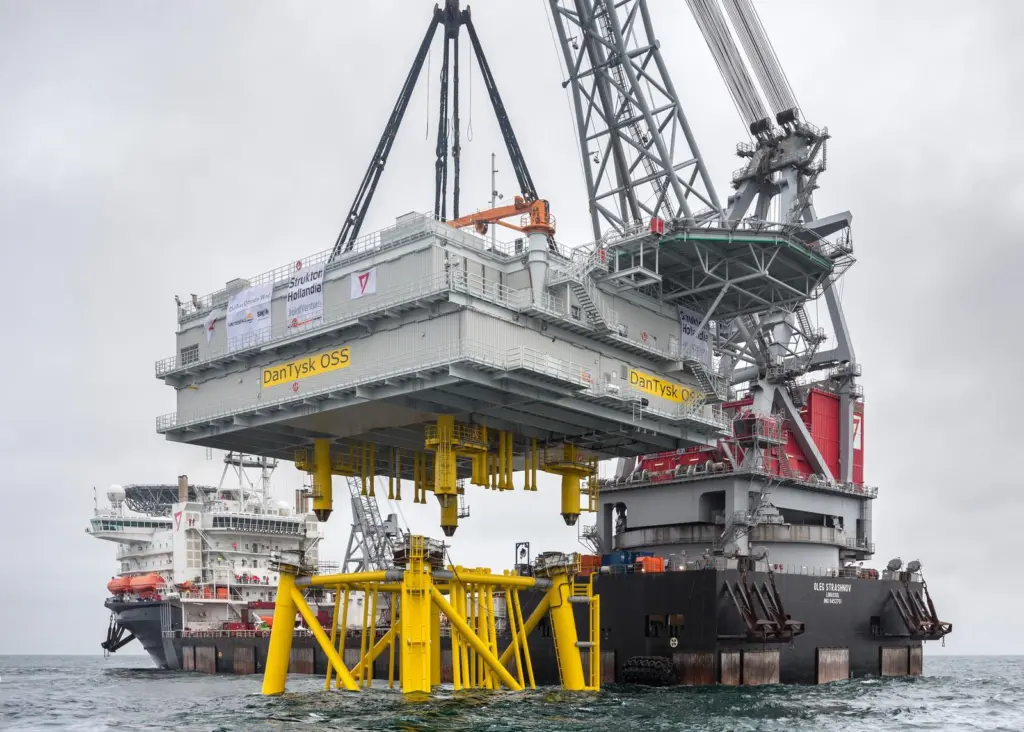
The German Offshore Wind Energy Foundation along with a list of seventeen prestigious industry partners have commissioned Prognos AG and The Fichtner Group to assess the potential for reducing the levelised cost of Germany’s offshore wind energy industry over the next ten years.
Germany is a significant player in European offshore wind. The industry’s prospects were boosted following the Fukushima nuclear accident in 2011 when the German government announced ambitious plans to phase out nuclear power and set a target of 35% of the country’s electricity consumption originating from renewables by 2020 and 80% by 2050. Of late it is proving to be a bumpy road however. Many of the country’s offshore wind sites are comparatively far offshore with subsequent cost implications, not to mention concerns at the strains being put on shore side grid networks by renewable energy generation. Their offshore wind ambitions are nonetheless important, the industry described as being at the beginning of its growth path. Around 2GW of capacity is currently under construction in the North and Baltic Seas with capacity expected to reach between 6GW and 10GW by 2020. Germany’s consumers already have some of the highest energy bills in Europe which in turn brings pressure on politicians and the industry. There is the risk however that development of offshore wind power is interrupted before the technology has reached its full potential through benefitting from learning effects. Put simply, reducing the cost of offshore wind is vital in the big picture of Germany’s energy supply mix, and indeed for the whole of Europe.
SCENARIOS
Two scenarios are considered. The first assumes a moderate development path with at least 9GW of accumulated installed capacity in Germany and a total of over 20GW in Europe by 2023, characterised by a long-term stable market environment. Scenario 2 assumes at least 14GW of installed capacity in Germany and a total of 40GW in the whole of Europe by 2023, figures that correspond to current political goals set for Germany and the EU. Scenario 2 also assumes that all technical cost reduction potentials have been realised alongside an optimum regulatory and competitive market environment. Other divisions within each scenario consider: various sites, dates of becoming operational, water depths varying from 30m to 50m, distances to port between 40km and 120km, and average wind speeds of between 9.9m/s and 10.1m/s. The configuration of windfarms also considers: various turbine numbers and capacities, windfarm size, hub height and rotor diameters.
Germany’s change of direction is known as ‘Energiewende’ or energy turnaround with the goal of reducing greenhouse gases by at least 80% by 2050 (relative to 1990) and is at the heart of the study, analysing the period between 2013 and 2023. It points out that while further cost-reducing development may occur post-2023 it is not currently possible to quantify them.
The first authoritative study of cost reduction potential in the industry was produced in the UK by The Crown Estate in 2012 and the design of the German study follows the same approach. Allowance has been made however for developments since, along with the fact that framework conditions of German offshore wind power are partially very different from those in the UK (regarding water depth, distance to port, grid connection and financing). Current turbine capacities are between 2.3MW and 6MW but with the prospect of 10MW turbines in the future the study calculates average turbine capacities of 4MW, 6MW and 8MW.
INVESTMENT COSTS
Estimates of the potential cost reductions from larger turbines reveal interesting possibilities. In scenario 1, investment cost reductions of up to 17% are suggested for 6MW turbines (by 2023) while the corresponding reductions for 8MW turbines in scenario 2 increase to 27%. Installation costs will decrease mainly due to improved logistics concepts, increased competition from new market entrants and larger turbine capacity. A point perhaps worth mentioning here is the predicted significant cost savings that floating turbine technologies could bring with the complete turbine structures themselves assembled and commissioned ashore, installation mainly involving towing to site, mooring and hooking-up.
The subject of operating costs is a complex area. Mention is often made of offshore wind being a maturing industry with gradual progress along the learning curve. The O&M phase however starts to happen further along the timeline. As more windfarms come on stream, each with its own particular set of circumstances, potential savings from optimisation of O&M elements become possible. Introduction of joint, inter-operator maintenance and logistics concepts is considered essential for realising large decreases in annual operating costs. This includes using joint fleet and logistics infrastructure such as landing and fuelling facilities for helicopters and ships, material storage and joint safety and rescue concepts. The report considers that sea-based maintenance concepts will become more efficient than land-based maintenance for windfarms more than 50km offshore. In scenario 1, annual operating costs are expected to decrease by one fifth over the next ten years. In scenario 2 with inter-operator maintenance concepts being applied to a larger extent, and turbine capacity increasing to 8MW, specific operating costs could go down by one third. Based on interviews with the report’s partners, from 2017 onwards insurance premiums are assumed to be constant in real terms.
For such capital-intensive technologies the cost of capital strongly affects the levelised cost of energy. It is considered that increasing project experience will reduce risk premiums and in the long term result in lower cost of capital for offshore wind projects. A financing workshop was held to establish a formula to determine the weighted average cost of capital and over the period considered and it is assumed such costs will decrease by more than two percentage points for projects becoming operational in 2023.
ENERGY GENERATION
The introduction of larger rotor diameters and hub heights over the period will see specific gross electricity generation increase by between 8% and 10% resulting in a substantially higher wind yield per turbine. The effects of increased internal and external wake losses however will result in a net electricity generation increase of between 3% and 6%. While there are natural advantages in locating windfarms in clusters thus taking advantage of grid connection benefits, careful consideration will need to be given to avoid external wake losses from adjacent windfarms, particularly as turbines become physically larger.
Reducing the levelised cost of energy from offshore wind is currently a subject of increasing importance, particularly with such figures being variously referenced as benchmarks for determining levels of government subsidies and support. The report concludes that by 2023 the levelised cost of offshore wind energy can be reduced to below 10 Cent/kWh. Three examples of sites featuring increasing water depth and distance to port are used, each predicting the trend of the levelised cost for each of the two scenarios. As to be expected, the trend with all three examples is downwards. Costs decrease on average by between 30% and 39% dependant on the variables and scenarios examined. It is pointed out that the reference year for basing the calculations for the two deeper and further seawards examples (2013) is rather theoretical as no windfarms with those parameters will be operational by the end of that year. Investments account for 75% of windfarm costs, the remainder being for operations and decommissioning. It is calculated this structure hardly changes over the period to 2023.
Examining cost reduction potentials, while more than half the potential savings can be attributed to investment costs, reducing O&M costs along with a decreased cost of capital offer the largest individual potential.
EXPLOITING POTENTIALS
As well as analysing the question of cost reductions touched on above, the report goes on to consider how to exploit the potentials. It is considered essential that all affected parties in industry, politics and administration are actively involved in realising the identified potential cost savings over the next ten years. What are described as the ‘technical areas’ such as investment and operating and decommissioning costs may be obvious themes but echoing what is now becoming a regular topic of comment by industry players themselves (not only in Germany), it is stated that a stable regulatory framework provided by the political environment is a prerequisite for progress.
Defining technical standards for plant components and grid connections can substantially reduce installation and maintenance costs it is concluded. The importance of close cooperation throughout Europe will further minimise costs through integration beyond Germany’s borders.
Optimisation of plant technology offers gains in utilisation and wind yield, and for sites close to shore, higher plant utilisation through larger rotors has advantages. The higher the maintenance costs from increased distances offshore, the more reasonable it becomes to maximise wind yield by the economies of scale larger turbine capacities contribute. The theme of optimisation continues with recommendations for standardising foundation design and production including higher volumes. The increased capabilities from larger installation vessels include better utilisation of favourable weather slots.
Related Articles
 MARINE RENEWABLES
 OFFSHORE RENEWABLES
 OTHER NEWS